
Martyn James: How to deal with storm and weather damage
Got to make an insurance claim? It will be a straightforward process if you follow Martyn James’s advice
What happens when I make an insurance claim for weather damage?
Insurance companies are relatively quick to begin investigations when there is significant damage as a result of a storm or bad weather. However, if lots of people in your local area are affected, this can have an impact.
Your insurer will initially send out a ‘loss adjuster’ to assess the damage and the repairs that need to be carried out as a priority. The loss adjuster will also provide a report laying out the subsequent repairs that will be required at a later stage.
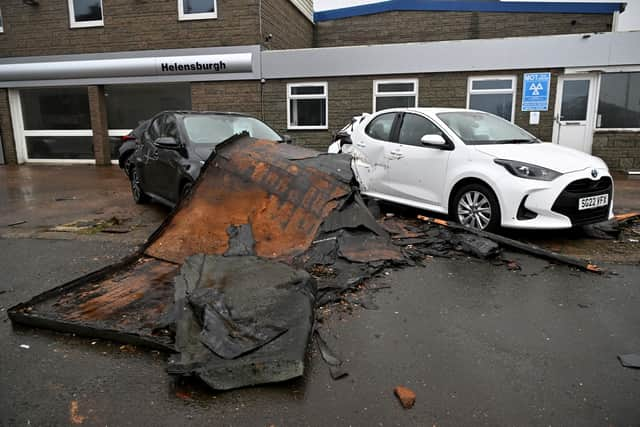

If you disagree with the assessment of the loss adjuster you should complain to the insurance underwriter as soon as possible.
How to make an effective home insurance claim for storm or weather damage
When your home is damaged it’s easy to feel a little lost. But don’t worry, there’s a straightforward process to making an insurance claim.
- Call your insurance company to log your claim as soon as you can, even if the problem with the storm or bad weather is still ongoing. Try to get as much practical advice from them as you can.
- Write down a few reminders before you call covering what’s gone wrong and the questions you want answering.
- Keep a record of any extra spending you’ve incurred during the incident, including hotel bills and emergency repair works, as this may be covered by your policy too.
- Make sure you keep your supporting documentation in a safe place with your insurance documents if you have them. Photo any key documents and receipts so you have a back up.
- Make a list covering the damage to your property and possessions. Take photographs too if you can.
How do I find out what will happen next?
Speak to the insurance company about what will happen next. Remember to ask about:
- What they are proposing (repairs, structural work, contents).
- Timescales.
- Accommodation if the property is uninhabitable.
- Special requirements (if you have medical conditions that affect where you can be rehoused).
- Contractors and their contact details.
- Security.
Don’t forget to ask for a dedicated contact telephone line with the insurance company that you can call for updates.
What other things do I need to bear in mind?
Don’t authorise your own contractors to carry out repairs without speaking to the insurer first. You might not be covered if your chosen contractor is more expensive than the insurer’s choice.
When you make a home and contents claim, make sure you explain the impact on you personally. This is particularly important if you’re ill or have a young family and you can’t stay in your property. Not only does it mean your claim will be dealt with more effectively, it will also personalise the case so the insurer understands the impact on you. The insurer should make special arrangements to suit your circumstances.
What can go wrong?
The biggest challenge with storm and flood complaints is the time it can take to sort things out, particularly if your property has been structurally damaged. During that time you may find yourself in alternative accommodation for a prolonged period.
Disputes with contractors, from loss adjusters to builders and specialist tradespeople are relatively common. Don’t forget, your contract is with the insurance company, so if you’re unhappy with a contractor, speak to the insurer.
What to do if you’re unhappy
If the insurance company doesn’t sort things out, you can take your complaint to the free Financial Ombudsman Service (FOS) who has the power to tell the insurer to make things right if they agree with your complaint. Make your complaint to the insurer first and if things aren’t resolved, tell them you are going to the ombudsman.
Martyn James is a leading consumer rights campaigner, TV and radio broadcaster and journalist. Visit martynjamesexpert.co.uk