
Why Scotland needs to write a new bank branch story
Routine transactions are going digital, so banks need to reimagine their physical presence around trust, advice and reassurance, says Stuart Chalmers
In Scotland, where the geography of banking is being rapidly redrawn, the debate about bank branch closures is often framed as a tug-of-war between nostalgia and efficiency. In the back and forth, we often miss a more fundamental question: how do people want to bank?
Most customers are happy for routine transactions to move to digital channels. But when the stakes rise, they still look for someone accountable and human. Branches remain the preferred channel for complex needs, applying for credit, opening a new account, or getting financial advice. This is about confidence; speaking to someone when the decision matters – although further to this, the debate is now in full flow about agentic assistants. This means AI that doesn't just provide information but executes tasks – which could reshape how people bank.
What is therefore changing is not the need for a branch but its role. Rather than simply shrinking their networks, banks should be reimagining their physical presence around trust, advice and reassurance.
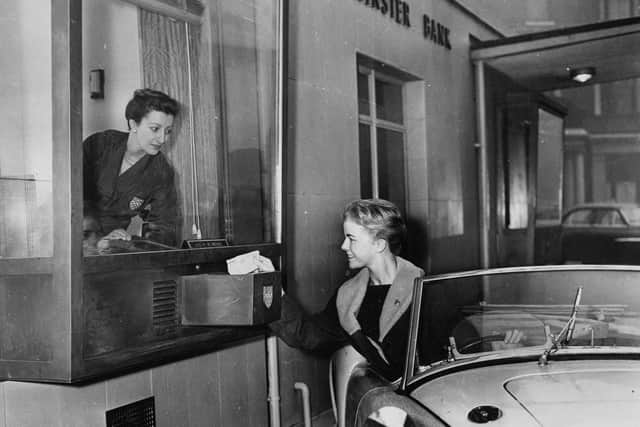

In Accenture’s latest UK-wide consumer banking research, two ideas point to where the market is heading. Nearly two-thirds of UK customers say they would use a bank branch reimagined as a ‘Life Orchestrator’, a trust hub where space and technology combine to help customers manage major life events. More than three-quarters say they would use micro branches or smart booths, secure small-footprint locations that bring essential services closer to where people live and work.
This local presence is a live issue in Scotland, where communities and small businesses can be hit hardest when the last branch in town closes. It is also why the strategy of players like Virgin Money remains in the spotlight. Recently acquired by Nationwide – but continuing to operate its distinct brand – Virgin Money has said it will keep its Scottish branches open. But keeping doors open is only the start. The bigger opportunity is to modernise what those doors lead to, and this is a question for all banks who maintain a physical footprint.
For households, a Life Orchestrator branch is less counter and queue and more private advice space. Conceptually, it offers life-stage planning tools and specialist support for the moments that define financial wellbeing, from buying a first home to caring responsibilities or retirement.
For Scottish SMEs, it means local help with cash flow, lending and fraud, with specialist expertise available quickly when needed. At a time when it is increasingly difficult to distinguish what is real from AI-generated content online, a physical location can signal safety and legitimacy.
Digital innovation must not slow down. Customers are willing to use AI assistants embedded in their bank app, with 73 per cent of UK customers noting that they would use a smart financial assistant. But as journeys become more automated, trust becomes more important. Customers want control: 84 per cent want to approve each AI action before it happens, and 77 per cent want a pause option they can use instantly.
Banks that introduce automation without transparent safeguards will erode confidence rather than build it. Physical channels can anchor this transition, offering a place to explain new tools, set permissions, and help customers recover quickly when something doesn’t feel right.
The best response to the digital shift is not to deny change, but to prove it can be designed around confidence. A strong Scottish model could combine advisory hubs in key towns and cities, supported by micro branches and smart booths in the communities they serve. Get the mix right and banks can keep trust rooted locally while delivering the speed and convenience the modern customer expects.
Stuart Chalmers is Consumer Industry Lead for the UK and Ireland and co-lead for Accenture in Scotland
Comments
Want to join the conversation? Please or to comment on this article.