
Dunelm targets more stores and £100m of cost cuts: shares slide
“Dunelm has announced an ambitious three-year strategic growth plan which aims to capitalise on the group’s obvious underlying strengths” – Richard Hunter, Interactive Investor
Homeware retailer Dunelm plans to strip some £100 million of “unproductive” costs from the business as part of a new three-year growth strategy that will also involve further store openings as it targets around 100 potential locations.
The cost-cutting programme will aim to make savings by the 2029 financial year through restructuring and changing internal processes.
The firm, which reported a 3.1 per cent rise in its annual sales, said work was already underway and, in the past three months, it has removed around 8 per cent of “central roles” within the business to “simplify the business and reduce central costs”. This amounts to some 95 job losses across its support functions and distribution.

Dunelm did not comment on whether there would be additional job cuts but said “further targeted cost removal” from restructuring over the next three years would deliver in the region of £40m of the annual cost savings.
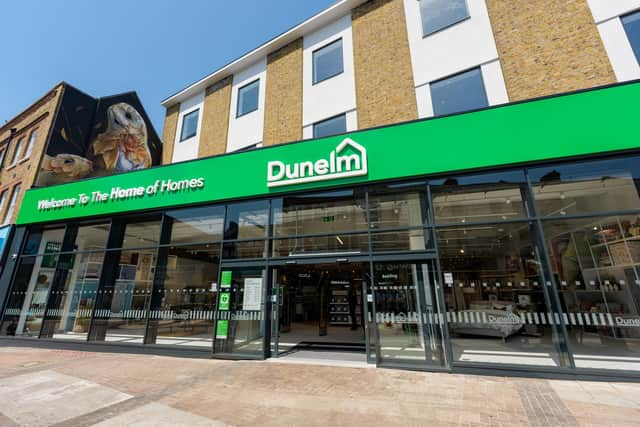
The firm’s three-year strategy also includes efforts to improve and simplify its product ranges, renew its chain of shops and open new ones.
Dunelm said it was targeting around 100 potential locations for new branches, with up to ten new openings per year for the next three years. Each store opening is expected to create around 50 jobs. It is also hoping to make greater use of artificial intelligence (AI) and automation to make processes more efficient, and plans to roll out radio-frequency identification (RFID) chips that are hidden in products to improve the accuracy and availability of stock.
The plans were unveiled after Dunelm said trading had been dampened because of unusually hot weather since the new financial year, which began at the end of June, affecting people’s shopping patterns.
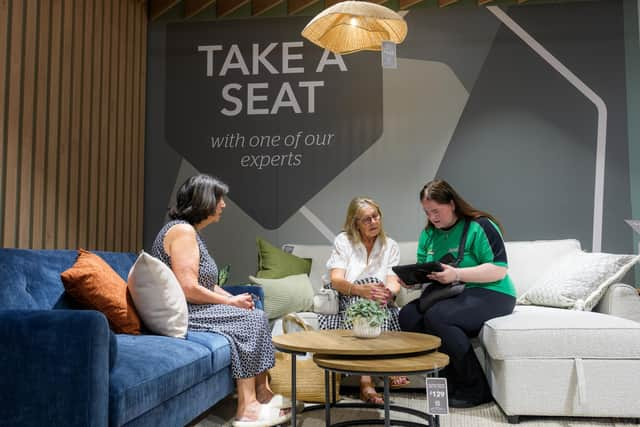
The retailer said it was continuing to see “challenging” conditions weigh on consumer confidence, including “elevated interest rates and inflation, and a changing UK political landscape”. This was leading to people shopping more selectively and increasingly hunting for value through promotions, particularly in non-essential spending like homeware.
Nevertheless, the company reported total sales of just under £1.83 billion for the year to June 27, up 3.1 per cent compared with the year before. Pre-tax profits were flat year-on-year at £211m.
Chief executive Clo Moriarty told investors: “We delivered a solid performance for the year, growing sales, maintaining profits and generating strong cash returns for shareholders.
“Over the last year, we have taken a deep and honest look at our business and the opportunities ahead to better serve our customers and drive the group’s performance. This work has given us confidence that the opportunity in front of Dunelm is larger than we previously understood, but also that we need to evolve.
“The strength of our business and balance sheet means we are well placed to invest for the future and accelerate our growth trajectory.
“By building on the proven strengths that have made Dunelm so successful and by developing the capabilities that will support the next phase of growth, we believe we can create a bigger, better and bolder Dunelm for all our stakeholders.”
Investors appeared somewhat underwhelmed and shares in the group had fallen about 12 per cent by lunchtime.
Richard Hunter, head of markets at Interactive Investor, part of Aberdeen Group, said: “Dunelm has announced an ambitious three-year strategic growth plan which aims to capitalise on the group’s obvious underlying strengths. As such, the results themselves have taken something of a back seat.
“This reset comes at a difficult time, with the propensity of consumers to spend under its own budgetary pressures and with rivals continuing to sharpen their offerings in what is a highly competitive space.
“The challenge therefore will be for Dunelm to consolidate the store offering to which it is clearly committed, alongside a revamped digital offering which reflects the tendency of customers to prefer an omnichannel experience.
“There is certainly much work to be done to arrest the slide of the shares over recent times,” he added.
Mark Crouch, market analyst for investment platform etoro, said: “Dunelm has kept its house in order through a difficult year for the British consumer, but with shares falling sharply, attention has quickly shifted to what comes next.
“The underlying business remains in decent health, with market share gains, stronger cash generation and growing digital penetration, but flat profits and a sharp slowdown in early trading have taken the shine off that resilience.
“Unusually hot weather undoubtedly gave shoppers fewer reasons to think about cushions and curtains, and trading has improved as temperatures cooled. But investors appear reluctant to blame the weather alone when household budgets remain stretched and the consumer backdrop uncertain,” he added.
“That puts considerably more pressure on Dunelm’s new growth plan. Stripping £100m of costs while investing to accelerate sales could create a leaner, stronger retailer, but it also brings execution risk.
“Dunelm has the brand and balance sheet to pull it off; after profits stalled and the shares stumbled, investors now want evidence that the makeover can deliver tangible growth.”
Chris Beauchamp, chief market analyst at investing and trading platform IG, noted: “Dunelm’s results demonstrate the difficulties retailers face in an environment of rising prices. While margins are better and sales are up, inflation means pre-tax profit was unchanged.
“Dunelm’s shares are down nearly 30 per cent in five years, with the dividend providing the only bright note for shareholders, so it’s good to see that being increased once again.”
Comments
Want to join the conversation? Please or to comment on this article.