Bank of Scotland owner Lloyds unveils profit and dividend hike but caution prevails after 40% share rise
“The big unknown remains the inquiry into mis-sold car financing products - and Lloyds is one of the most exposed financial institutions” – Zoe Gillespie, RBC Brewin Dolphin
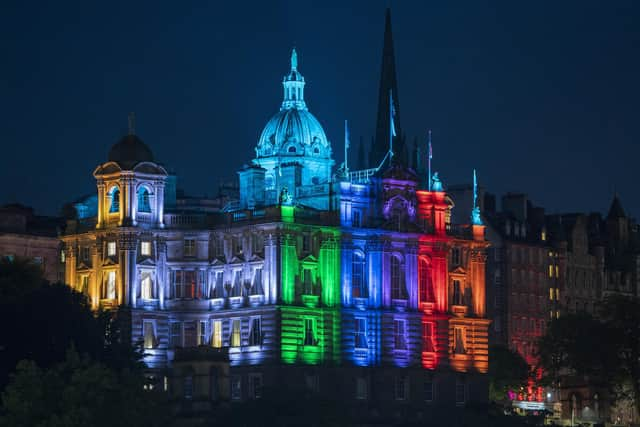
Bank of Scotland owner Lloyds Banking Group has unveiled better-than-expected first-half profits as it benefited from a jump in lending and savings balances.
The FTSE-100 group, which ranks as the UK’s largest mortgage lender and also incorporates Halifax and Scottish Widows, reported a pre-tax profit of £3.5 billion for the first six months of the year - 5 per cent higher than a year ago. Earnings for the first half also came in ahead of the £3.2bn analysts had anticipated.
Lloyds said total lending to customers increased by £11.9bn over the period, or 3 per cent, driven by UK mortgages with some 33,000 first-time buyers borrowing on a home.

Customer deposits grew by £11.2bn, or 2 per cent, following a strong season for ISAs, while more people moved money out of current accounts and into savings.
Meanwhile, Lloyds confirmed there had been no change to its motor finance provision, having set aside some £1.2bn to cover potential costs and compensation related to commission arrangements. The group is exposed to the motor finance market through its Black Horse business.
Group chief executive Charlie Nunn told investors: “We have shown sustained strength in our financial performance in the first half of 2025, with income growth, cost discipline and robust asset quality, driving strong capital generation and increased shareholder distributions, with a 15 per cent increase in the interim ordinary dividend.
“We continue to make great progress in our purpose-driven strategy, building differentiated customer outcomes and delivering growth across our business as we build towards our ambitious targets for 2026.”
Zoe Gillespie, wealth manager at RBC Brewin Dolphin, said: “Lloyds has delivered another strong set of results, with profits and income beating expectations. Despite interest rates being on a downward trajectory, the bank has also managed to strengthen its net interest margin and secure more customer deposits in a competitive UK banking environment.
“That said, the big unknown remains the inquiry into mis-sold car financing products - and Lloyds is one of the most exposed financial institutions. The shares are up more than 40 per cent in the year to date, which reflects the solid progress made in its core business, but the car finance issue may put a brake on the bank until its impact is clearer.”
Chris Beauchamp, head of market analysis at IG Group, sounded a note of caution, saying: “After a 40 per cent share price rise this year, the reference to ‘economic deterioration’ in today’s Lloyds’ numbers looks like commendable caution. There’s still much to like in the figures overall, not least the bigger dividend, and the 2015 highs in the share price still look attainable, but it wouldn’t be surprising to see some consolidation for the time being.”
Garry White, chief investment commentator at Charles Stanley, added: “Lloyds’ results paint a picture of resilience, despite revenue coming in modestly below expectations. The second half of the year could get more difficult, but right now it seems Lloyds is holding on a steady course.”
Rival NatWest Group, owner of Royal Bank of Scotland and formerly called RBS Group, is due to report on Friday.
Comments
Want to join the conversation? Please or to comment on this article.