
Are we sleepwalking into a financial advice crisis?
Fewer people than ever are putting their cash into investments, and that’s a problem for the future, writes Adrian Murphy
The UK’s aversion to investing is no secret. Some £2 trillion is estimated to sit in bank accounts, gradually losing its value in real terms. What you could buy with £1,000 in 2016 now costs £1,398, meaning you would have had to achieve a return of 3.35% over those 10 years to maintain the real-terms value of your wealth - an almost impossibility through cash, given interest rates were near enough zero for half that time. If history repeats itself, UK savers could lose £796 billion of purchasing power by 2036.
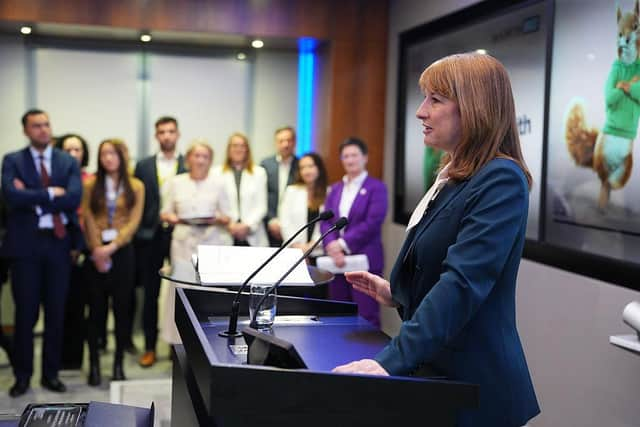
After years of failed attempts to softly change attitudes, there are reasons to believe our national antipathy towards putting our money in stocks and shares could be on the turn. The UK Government recently launched its ‘Savvy the Squirrel’ marketing campaign to do just that at a cost of up to £30 million. Before that, the Investment Association’s Risk Warnings Review, commissioned by Chancellor Rachel Reeves, recommended moving away from the generic – and off-putting – disclaimers applied to investment products.
Both are positive, long overdue moves. Far too many people in the UK hinder their own financial futures by opting to keep their wealth in cash, believing it is the safer option. Studies have shown that around half of people don’t understand that their money loses purchasing power over time because of inflation, and 60% choose not to invest because they believe it’s too risky. As a result, outside of pensions, less than one-quarter of the UK invest in stocks and shares, compared to two-thirds of Americans.

Words matter – the way we have labelled investments is undoubtedly part of the story. One recent poll suggested nearly three-quarters of savers felt deterred from investing by the ‘capital at risk’ warning that has become so ubiquitous. The use of ‘high risk’ to describe pension products that have more equity exposure than others – despite the fact they contain hundreds, if not thousands, of different investments – is similarly counterproductive.
The surge in new accounts being opened on DIY personal finance platforms during the last few months suggests the message is getting through. While more people showing an interest in investing, and taking the first steps towards actively doing so, is encouraging, there are other foundations that need to be laid – and the most important is an understanding of what it is and is not.
The fact of the matter is that, as a nation, we need to know more about investment before we can make the right choices for our financial futures. According to a recent survey, around two-thirds, 61%, of people in the UK said they found investing confusing and difficult to understand – up on 44% a decade ago. Even more, 65%, are unwilling to invest because they feel it is too risky. And 34% of respondents told another poll that they fear losing all the money they invest.
All of these statistics demonstrate the lack of fundamental understanding in the UK when it comes to investing. If making the country a nation of investors is going to work the way policymakers intend, we need to make financial education and advice available and accessible to more people at all stages of their life. That starts in schools, should continue into university, and evolve as needs and the role money plays in people’s lives over time change.
At the moment, we’re asking people to do something too many of them do not understand. The perception of investing is as a high-risk game of picking a winning stock from thousands of options – but the reality is much more mundane. It involves investing over time in a broad range of assets, building your wealth slowly but surely. There will inevitably be bumps and dips along the way – and that’s why investors earn a return – but time and again a recovery has followed and the general direction of markets has been up and to the right.
You can’t shift deep-seated views overnight. Like the endeavour of building wealth itself, turning a nation of savers into one of investors needs to be thought about in the long term, built on a foundation of education, a change in the culture of how we think and talk about money, as well as access to advice as people’s circumstances change.
Adrian Murphy, CEO of Murphy Wealth
Comments
Want to join the conversation? Please or to comment on this article.